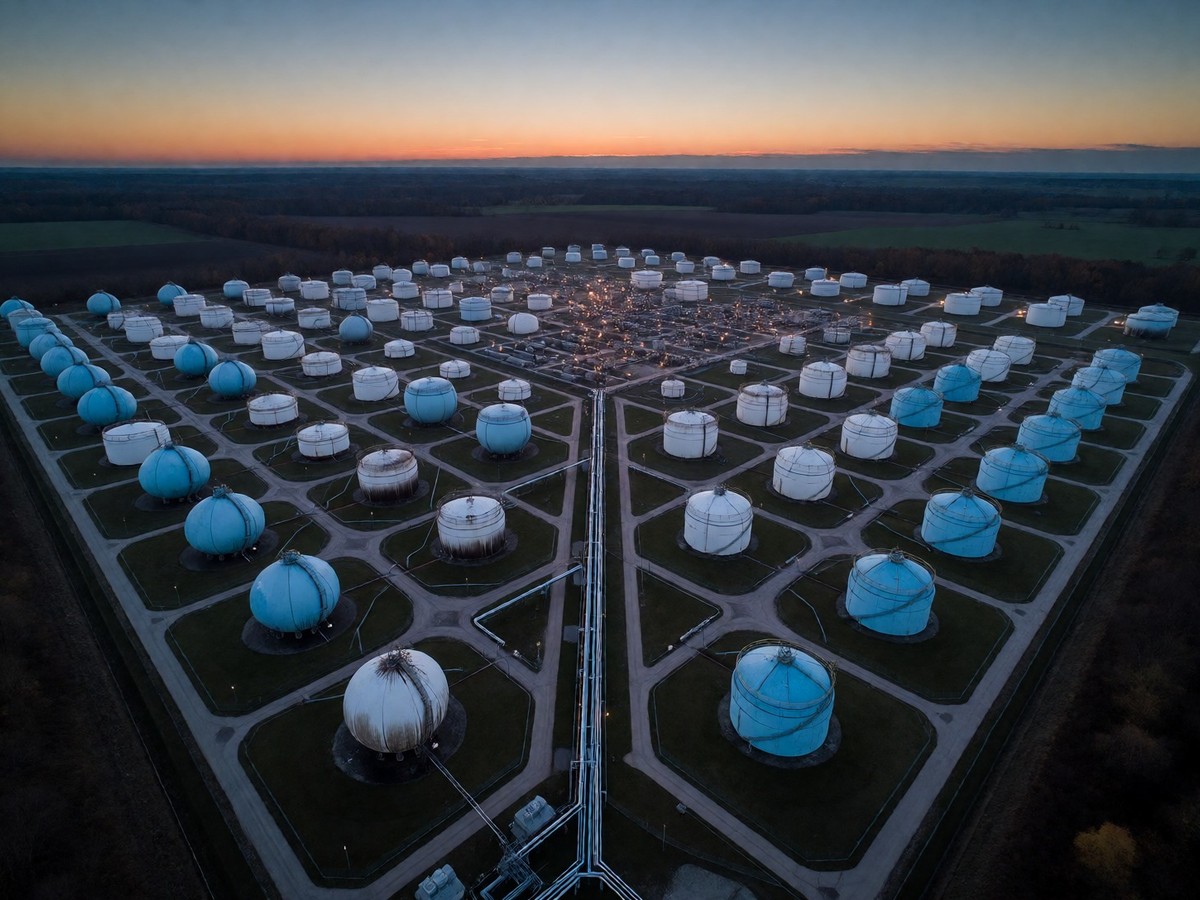
The European Union enters the heating season with a critical shortfall, holding only 77% of tank capacity against the mandated 90% benchmark. Germany missed this target by a wide margin, leaving the bloc’s net draw to grow almost fivefold in five days. The surge in withdrawals comes from the smallest stock on record for the date, deepening the crisis set off by the closure of the Strait of Hormuz. I see no safety buffer here; the current trajectory suggests a severe winter ahead for consumers and industry alike.
Record withdrawals meet low reserves
GIE data shows that 13 of the EU’s 18 storage countries were drawing down on November 6, compared to just 10 on November 1. The swing is most visible in Germany, where the largest store took 1,088 GWh out on November 6 after putting in 32 GWh on November 1. Poland and Denmark flipped to withdrawal mode with it, while Spain and Latvia stopped injecting without yet drawing. France has drawn hardest against its own size, down 4.41% of capacity, whereas Poland remains 98.1% full and has barely started. These records apply to the specific date only, as the highest daily withdrawal in the series remains about 11.7 TWh from February 2018. However, gross withdrawals on November 5 reached 4.33 TWh, which is 31% above the same day in 2021. The gap represents about 97 million cubic metres, a significant jump that confirms the acceleration in demand.
Turkish deliveries and price pressures
Gazprom reports that pipeline deliveries to Turkey in the first five days of November were almost four times those of the same days in October and September. Kommersant noted that October’s total was 78% above September’s, though Gazprom gave no volumes for Turkey. This surge coincides with Ankara arguing over price, as Energy Minister Alparslan Bayraktar stated on November 5 that Turkey is buying less Russian gas because it is expensive. The contracts expire at the end of 2026, adding urgency to the negotiations. Meanwhile, prices have eased from their peak but remain high, with the front-month Dutch TTF contract at about €90 per MWh on November 4. This follows a spike topping €100 on October 28. Alexei Miller warned on October 30 that European gas could hit $2,500 per 1,000 cubic metres, a figure that seems plausible given the current strain. The IEA warns that stocks may fall below 10% by March if the winter is cold and Hormuz LNG does not return. At the current draw rate, only a mild winter like 2022-23 would leave as much as 35% capacity.